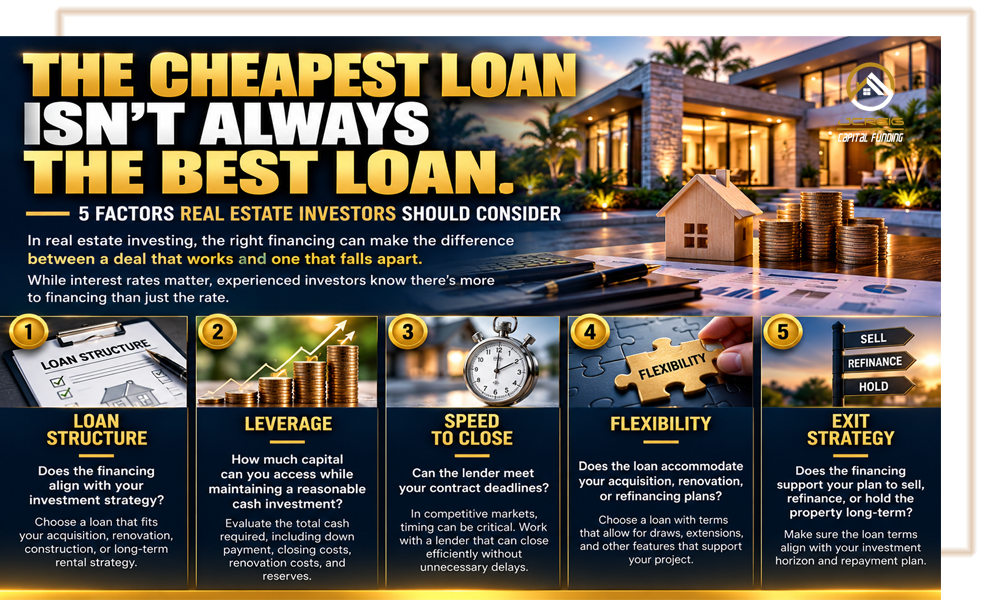
Choosing the right financing can make the difference between a profitable investment and a deal that falls short of expectations. While interest rates are important, experienced real estate investors understand that the lowest rate does not always translate into the best financing solution.
The loan you choose can affect your cash requirements, closing timeline, renovation budget, investment flexibility, and overall profitability. Looking beyond the advertised interest rate can help you make more informed financing decisions and position your next investment for success.
At JCREIG Capital Funding, we understand that every investment property, borrower, and business strategy is different. Our goal is to help real estate investors explore financing options that align with their objectives and the unique requirements of their deals.
In this article, we’ll examine five important factors to consider when comparing real estate investment loans.
1. Loan Structure: Does the Financing Fit Your Investment Strategy?
Not every real estate investment requires the same type of financing. The right loan depends on the property, your business plan, the work required, and your intended exit strategy.
For example, an investor purchasing a distressed property may need short-term financing for the acquisition and renovations. An investor purchasing a stabilized rental property may be looking for long-term financing based primarily on the property’s rental income. Meanwhile, a developer constructing a new property may require a loan structured around construction costs and project milestones.
Choosing a loan that does not align with your investment strategy can create unnecessary expenses, delays, or financial pressure.
Before selecting a lender, consider the following questions:
- Does the loan cover the acquisition, renovation, or construction costs required for the project?
- Is the loan term appropriate for your anticipated holding period?
- Are the payment requirements manageable during the investment?
- Does the financing accommodate your plans to sell, refinance, or hold the property?
- Are there prepayment penalties, extension fees, draw requirements, or other terms that could affect your returns?
The key is to select a financing structure that supports your business plan rather than forcing your business plan to accommodate the loan.
At JCREIG Capital Funding, we work with a network of lending sources to help investors explore financing options for a variety of investment strategies, subject to lender and program guidelines.
2. Leverage: How Much Capital Will You Need to Invest?
Leverage allows real estate investors to purchase and improve properties using borrowed funds rather than relying entirely on personal capital.
Used appropriately, leverage can help investors preserve liquidity and pursue additional opportunities. However, higher leverage also increases financial obligations and may increase the risk associated with an investment.
When comparing loans, do not focus exclusively on the maximum loan amount or loan-to-value ratio. Consider how much cash you will need to bring to the closing table and maintain throughout the project.
Your total capital requirements may include:
- Down payment or required equity contribution.
- Closing costs and lender fees.
- Appraisal, inspection, title, and other third-party expenses.
- Renovation or construction costs not covered by the loan.
- Interest payments and financing reserves.
- Insurance, taxes, utilities, and carrying costs.
- Contingency funds for unexpected repairs or delays.
Why the Total Cash Requirement Matters
Consider two hypothetical financing offers for the same investment property.
One lender offers a lower interest rate but requires a larger cash contribution. Another offers a higher interest rate but may provide greater leverage or fund a larger portion of the eligible renovation budget.
The second option could preserve more of the investor’s cash, but it is not automatically the better choice. Higher fees, additional interest expense, or stricter loan terms could offset that benefit.
The investor must evaluate the complete cost of each financing option against the property’s projected returns and the value of retaining liquidity.
Smart leverage is not simply about borrowing more. It is about understanding how borrowed capital affects your investment, cash flow, and overall risk.
3. Speed to Close: Can Your Lender Meet Your Timeline?
In competitive real estate markets, timing can be critical.
An attractive investment property may receive multiple offers, and sellers may prioritize buyers who can demonstrate their ability to close within the required timeframe. Delays in financing can complicate negotiations, increase holding costs, or put a transaction at risk.
For investors purchasing distressed properties, time can be especially important when a property requires immediate repairs or when a contract includes a short closing deadline.
When evaluating a lender, ask about:
- Typical closing timelines for the specific loan program.
- Documentation required to begin underwriting.
- Appraisal, title, and property inspection requirements.
- How quickly the lender reviews the property and proposed business plan.
- Whether renovation budgets and contractor estimates must be approved before closing.
- Potential conditions that could delay funding.
Is Faster Financing Always Better?
Not necessarily. A fast closing is valuable only when the financing also fits the investment.
Investors should understand the loan terms, fees, repayment obligations, and approval conditions before proceeding. Rushing into a financing arrangement without reviewing the details can create problems that outweigh the benefit of closing quickly.
Hard money and bridge loans may offer streamlined financing for eligible investment transactions, but actual closing times vary based on the property, borrower, documentation, underwriting, and lender requirements.
At JCREIG Capital Funding, we recognize that timing matters. We help investors explore financing options designed for different property types and investment scenarios.
A strong financing strategy considers both how quickly you can close and whether the loan supports the investment after closing.
4. Flexibility: Can the Loan Accommodate Your Project?
Real estate investments rarely follow a perfectly predictable path.
Renovations may uncover unexpected repairs. Construction schedules may change. Material costs can fluctuate. Rental properties may take longer than expected to stabilize.
These possibilities make it important to understand how a loan handles the specific requirements of your project.
Depending on the program, financing flexibility may involve:
- Eligible acquisition and renovation costs.
- Construction draw schedules.
- Requirements for inspections before funds are released.
- Extension options if a project takes longer than anticipated.
- Refinancing eligibility and repayment requirements.
- Permitted property types and ownership structures.
- Requirements related to occupancy, rental income, or property condition.
Not every lender offers the same options, and flexibility may come with additional costs or conditions.
For example, an investor completing a major renovation should understand how the lender disburses renovation funds, what documentation is required for each draw, and whether the available funding schedule aligns with the contractor’s payment requirements.
Likewise, an investor purchasing a rental property should understand the requirements for transitioning from short-term financing to a longer-term loan, if that is the intended strategy.
Understand the Terms Before You Commit
A loan may appear attractive at first but become less suitable once you account for its restrictions.
Ask your lender to explain the terms that matter most to your project, including fees, draw procedures, extension provisions, repayment requirements, and any conditions that could affect your exit strategy.
The right financing should support your investment plan while helping you understand the risks and obligations involved.
5. Exit Strategy: How Will You Repay the Loan?
One of the most important questions in real estate investing is also one of the easiest to overlook:
How will you repay the loan?
Before acquiring a property, investors should identify a realistic exit strategy and evaluate whether the financing supports that plan.
Common real estate investment strategies include selling after renovations, refinancing into long-term financing, or holding a property to generate rental income.
Each approach has different financial considerations.
Fix-and-Flip Investments
An investor purchasing a property to renovate and resell should evaluate the anticipated renovation timeline, projected resale value, selling expenses, interest costs, and other carrying costs.
The investment should account for potential delays and unexpected expenses rather than relying solely on an optimistic resale estimate.
BRRRR Investments
The BRRRR strategy—Buy, Rehab, Rent, Refinance, Repeat—involves acquiring a property, renovating it, renting it, and then pursuing a refinance before using available capital toward another investment.
An investor may initially use short-term acquisition and renovation financing before exploring a Debt Service Coverage Ratio (DSCR) loan for the rental property.
DSCR financing generally evaluates the property’s rental income relative to its debt obligations, subject to the lender’s underwriting requirements and program guidelines.
However, a future refinance is never guaranteed. The property’s appraised value, rental performance, market conditions, interest rates, borrower eligibility, and lender requirements may affect the available terms.
Investors should evaluate whether they can manage the investment if refinancing takes longer than expected or does not produce the anticipated proceeds.
Long-Term Rental Investments
Investors planning to hold properties for rental income should examine projected cash flow, financing costs, property expenses, and debt obligations.
The objective is to understand whether the property can support the investment over time, including during periods of vacancy, unexpected maintenance, or changing operating expenses.
Commercial Real Estate Investments
Commercial properties may require a different approach depending on the asset type, lease structure, tenant profile, operating income, and intended holding period.
Investors should understand the loan’s repayment terms and evaluate whether the property’s projected income and the investor’s business plan support those obligations.
Your exit strategy should influence your financing decision from the beginning—not become an afterthought once the loan is in place.
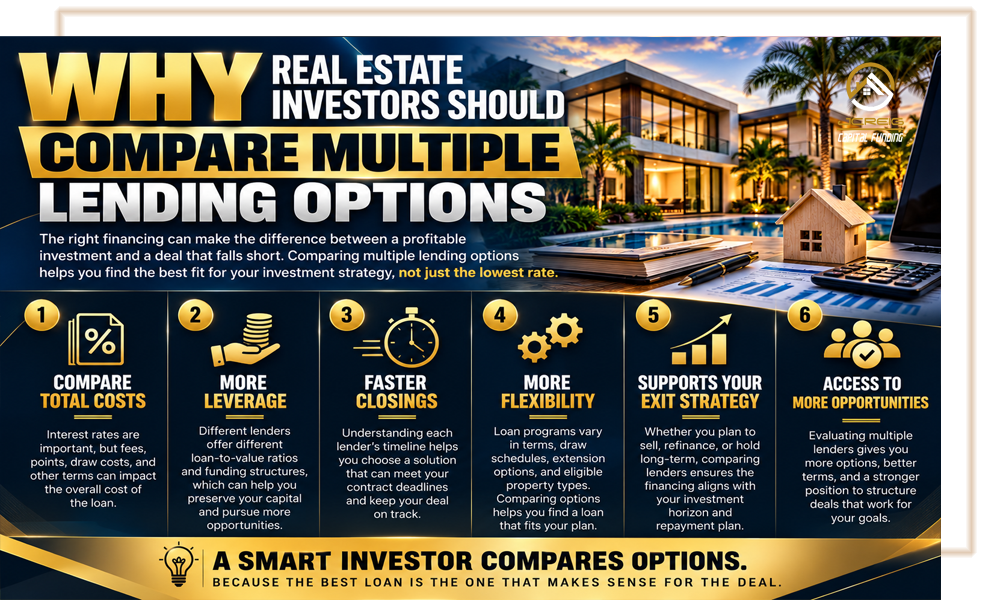
Why Real Estate Investors Should Compare Multiple Lending Options
Real estate investors have different objectives, experience levels, capital resources, and property requirements. A financing program that works well for one transaction may not be appropriate for another.
Comparing multiple lending options can help investors better understand the available structures, costs, requirements, and potential trade-offs.
At JCREIG Capital Funding, we leverage an extensive network of lending sources to help real estate investors explore financing solutions for a variety of investment opportunities.
Our goal is to help you evaluate potential options based on your property, investment strategy, and financing needs.
Our Real Estate Investment Financing Options
For eligible investors acquiring properties to renovate and resell, or pursuing other approved renovation strategies.
Short-term financing options for qualifying investment properties and transactions that require interim capital.
Financing options for eligible rental properties, with qualification based primarily on property cash flow under applicable program guidelines.
Financing options for qualifying ground-up construction projects, subject to project, borrower, and lender requirements.
Financing options for eligible commercial properties, including select multifamily, mixed-use, office, retail, industrial, and other investment property types.
Program availability, leverage, pricing, loan terms, documentation, and eligibility vary by lender and transaction. All financing is subject to underwriting and applicable program guidelines.
How to Prepare Before Requesting Financing
Investors can often make the financing process more efficient by organizing important deal information before approaching a lender.
While each loan program has different requirements, consider preparing the following:
1. Property Information
The property address, purchase price, property type, current condition, and relevant details about the transaction.
2. Investment Strategy
Explain whether you intend to renovate and sell, construct a property, acquire a rental, refinance an existing investment, or pursue another strategy.
3. Project Budget
For renovation or construction projects, prepare an estimated budget and scope of work. Include a contingency for unexpected expenses.
4. Property Valuation and Income Projections
Provide available comparable sales, an estimated after-repair value where applicable, or rental income information relevant to the financing request.
5. Timeline and Exit Strategy
Identify your anticipated closing date, project timeline, and planned repayment strategy.
6. Borrower and Ownership Information
Be prepared to provide the financial, experience, entity, and property documentation required by the selected loan program.
Having this information available can help a lender evaluate the opportunity and determine which financing options may be appropriate.
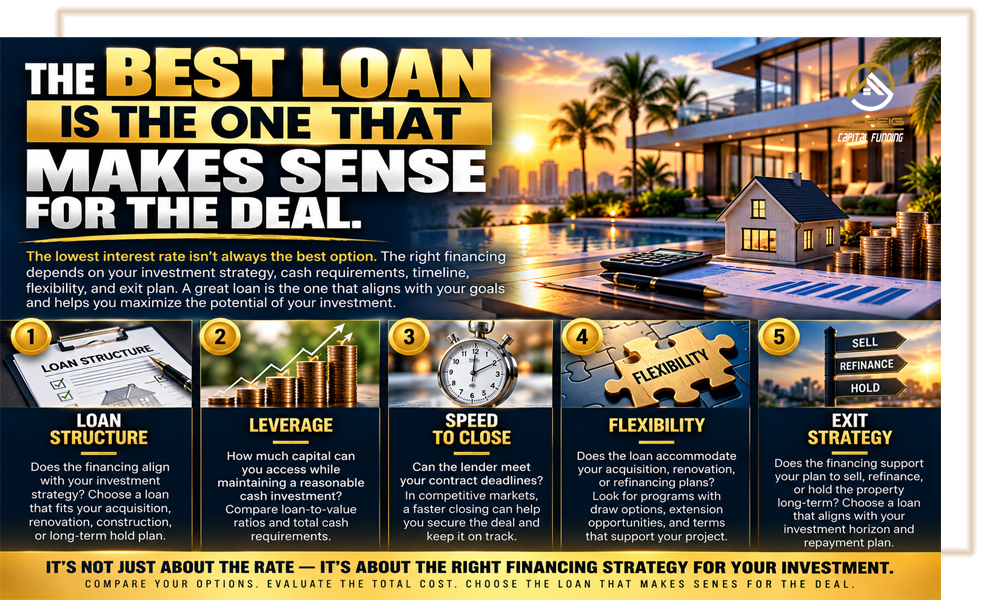
The Bottom Line: The Best Loan Is the One That Makes Sense for the Deal
The lowest interest rate can be appealing, but it does not tell the whole story.
Before choosing a lender, evaluate the loan structure, required cash investment, closing timeline, flexibility, total financing costs, and exit strategy.
Consider how each factor affects the property’s projected performance and your ability to manage the investment responsibly.
A loan with a slightly higher rate may be worth considering if its overall structure better supports the project. Conversely, a lower-rate loan may be the better choice when its terms, costs, and requirements align with your goals.
The important thing is to compare the complete financing package rather than making a decision based on one number.
At JCREIG Capital Funding, we believe informed investors make stronger financing decisions. Our team works with a network of lending sources to help investors explore options for acquisitions, renovations, rental properties, construction projects, and commercial real estate investments.
Have a Real Estate Investment Deal You’d Like to Discuss?
Whether you have a property under contract, are evaluating your next acquisition, or want to compare financing options for an existing investment, we welcome the opportunity to learn more about your goals.
Let’s review the deal, discuss your financing needs, and explore potential solutions.
JCREIG Capital Funding
Connecting Opportunities With Real Funding.📞 Phone: 561-303-0334
🌐 Website: JCREIG Capital Funding
📅 Schedule a Call: Schedule a Financing ConsultationLet’s run the numbers and see what we can do.
FAQs
One of the biggest mistakes is overpaying for the property. If the acquisition price is too high, even a successful renovation and resale may not produce an adequate profit. Investors should analyze the purchase price, rehab costs, financing, holding costs, selling expenses, and realistic ARV before making an offer.
ARV stands for After Repair Value. It is the estimated market value of a property after the planned renovations have been completed. ARV is commonly used by investors and lenders when evaluating the potential economics and financing of a fix-and-flip project.
ARV is generally estimated by analyzing recently sold comparable properties that are similar in location, size, layout, condition, and features. Investors should avoid relying solely on the highest-priced property in the neighborhood and should consider realistic comparable sales.
There is no universal contingency percentage that works for every project. The appropriate reserve depends on the property’s age, condition, renovation scope, location, and level of uncertainty. A contingency should be included in the project budget so an unexpected repair does not immediately eliminate the investor’s projected profit.
Holding costs are the expenses associated with owning the property while it is being renovated and prepared for sale. They can include loan interest, property taxes, insurance, utilities, HOA fees, lawn maintenance, security, and other property-related expenses.
Every additional month can increase the cost of a project. Extended timelines can result in additional interest, taxes, insurance, utilities, contractor expenses, and other carrying costs. Investors should evaluate what happens to the deal if the project takes 30, 60, or 90 days longer than expected.
Investors should evaluate a contractor’s relevant experience, references, licensing and insurance requirements, previous projects, scope of work, payment schedule, estimated completion time, subcontractors, and change-order procedures. The lowest bid is not necessarily the best choice.
LTC stands for Loan-to-Cost. It measures the loan amount relative to the total project cost. Depending on the lender and program, project costs may include the acquisition price and eligible renovation expenses.
For example, if the total project cost is $300,000 and the loan is $240,000:
$240,000 ÷ $300,000 = 80% LTC
LTC requirements and calculations vary by lender and loan program.
LTV stands for Loan-to-Value. It compares the loan amount to the value of the property. In fix-and-flip financing, lenders may also consider the property’s projected value after renovation, commonly referred to as ARV, subject to program guidelines.
Yes. Some fix-and-flip hard money programs can provide financing for both property acquisition and eligible renovation costs. The exact amount available, draw structure, LTC, ARV limitations, and borrower requirements vary by lender and program.
When a lender finances renovation costs, those funds may be released in stages as work is completed. The lender may require inspections, documentation, invoices, or other evidence that the renovation milestones have been completed.
Investors should understand the lender’s draw process before closing and coordinate the construction schedule with the contractor.
No. Investors should evaluate the entire cost and structure of the loan, not just the interest rate.
Important factors can include:
- Interest rate
- Origination fees
- Points
- LTC
- LTV or ARV limitations
- Rehab financing
- Draw procedures
- Closing costs
- Extension terms
- Minimum interest
- Prepayment provisions
- Required reserves
- Closing speed
A loan with a slightly higher rate may potentially be more useful if its overall structure better fits the project.
A delayed project can increase holding and financing costs and may reduce your final profit. Depending on the circumstances and loan terms, investors may need a loan extension, additional reserves, or another exit strategy.
This is why investors should stress-test the deal before closing.
A backup exit strategy is an alternative plan for disposing of or financing the property if the original plan does not work.
For a fix-and-flip investor, the original plan may be to renovate and sell. Depending on the property and qualification requirements, alternatives could include selling to another investor, refinancing into long-term rental financing, or retaining the property as a rental.
Potentially, yes. Investors who decide to keep a renovated property as a rental may be able to refinance into a DSCR loan if the property, borrower, and loan meet the applicable program requirements.
DSCR financing can be particularly useful for investors who want to qualify based primarily on the property’s rental income rather than traditional personal-income documentation, subject to lender guidelines.
There is no single profit amount that makes every flip worthwhile. The required profit should account for the investor’s risk, capital, financing costs, renovation complexity, timeline, market conditions, and potential downside.
A deal with a $75,000 projected profit may be less attractive than a $50,000 deal if the first project carries substantially more risk.
Gross profit is generally the difference between the acquisition price and resale price.
Net profit accounts for the additional expenses required to complete and sell the project.
A simplified calculation is:
Net Profit = Sale Price − Purchase Price − Rehab − Financing − Holding Costs − Selling Costs − Other Project Expenses
Investors should focus on projected net profit, not simply the difference between purchase price and resale price.
Commonly overlooked expenses can include:
- Loan interest
- Loan fees
- Property taxes
- Insurance
- Utilities
- Permit fees
- Inspection fees
- Dumpster costs
- Landscaping
- HOA fees
- Realtor commissions
- Seller closing costs
- Title expenses
- Loan extension fees
- Unexpected repairs
- Contractor change orders
A complete project budget should account for these expenses before the investor closes.
Not necessarily. Renovations should generally be appropriate for the property’s neighborhood and target buyer.
Over-improving a property can result in spending more money than the market will recognize in the final sale price.
The goal is not necessarily to build the most expensive house in the neighborhood. The goal is to create a property that is competitive with the homes buyers are actually purchasing.
The required amount depends on the financing structure, down payment, renovation costs, reserves, closing expenses, and lender requirements.
Even when a lender finances a significant portion of the project, investors should consider maintaining liquidity for unexpected expenses, draw timing, cost overruns, and extended holding periods.
Yes. Ideally, investors should understand their financing options before submitting an offer.
Knowing your potential loan amount, required equity, rehab financing, estimated costs, and closing timeline can help you determine whether a deal actually works before you commit to the purchase.
Potentially. Requirements vary by lender and program. Some programs place greater emphasis on prior investment experience, while others may consider first-time investors under certain circumstances.
Investors should discuss the specific property, renovation scope, financial profile, and exit strategy with the lender before assuming they will or will not qualify.
There is no universal credit-score requirement. Minimum credit scores and other qualification criteria vary by lender, loan program, property type, loan amount, experience, and overall transaction strength.
A strong deal may be evaluated differently from another project with higher risk.
Depending on the lender and program, fix-and-flip financing may be available for various investment properties, including certain single-family homes, townhomes, condos, and multifamily properties.
Property eligibility varies, so investors should confirm that the specific property qualifies before proceeding.
There is no way to eliminate investment risk, but investors can reduce avoidable risk by:
- Buying at the right price.
- Using realistic comparable sales.
- Accurately estimating the renovation.
- Including a contingency.
- Choosing qualified contractors.
- Understanding financing costs.
- Accounting for holding costs.
- Maintaining adequate reserves.
- Stress-testing the project timeline.
- Having a realistic exit strategy.
The best flips are usually built on conservative numbers—not optimistic assumptions.
Before you put your next investment property under contract, make sure you understand both the deal economics and the financing structure.
JCREIG Capital Funding provides financing solutions for real estate investors, including fix-and-flip, bridge, DSCR, ground-up construction, multifamily, commercial, and other investor loan programs.
Fix & Flip Financing
Depending on the program and transaction, financing may include:
- Up to 90% LTC
- Up to 100% of eligible rehab costs
- Up to 70% ARV
- Loan amounts starting at $100,000
- No income documentation on qualifying programs
- Fast closings
- Minimal documentation
Call JCREIG Capital Funding:
(561) 303-0334
Visit:
www.jcreigcapitalfunding.com
Don’t just find a property. Find a deal that makes sense.